Schenley Park Flood Zone & Flood Insurance Guide 2026 (Miami FL 33155)
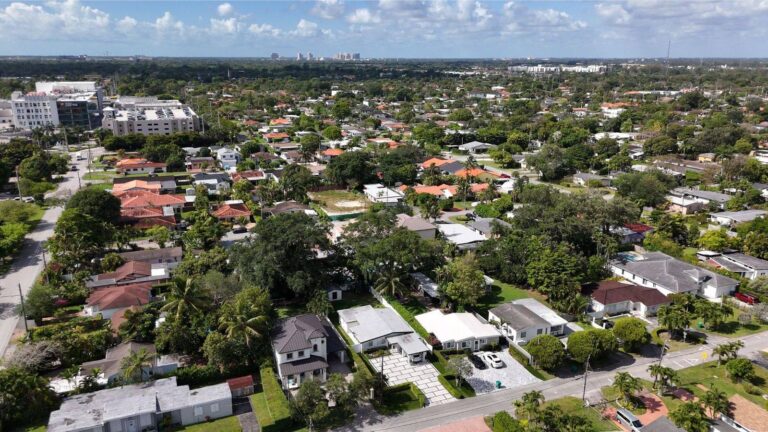
Is Schenley Park in a flood zone? Under today’s FEMA maps, the Schenley Park and Coral Terrace area of Miami, FL 33155 is in Zone X, the lowest-risk designation, so most lenders will not require flood insurance. Lowest risk is not no risk: your homeowners policy does not cover flood, a policy here is usually inexpensive, and since 2024 Florida requires every seller to give the buyer a written flood disclosure at or before the contract is signed. Here is what that means if you are buying, selling or staying.
By Berenice Elguezabal | October 12, 2026
What Zone X means for a Schenley Park home
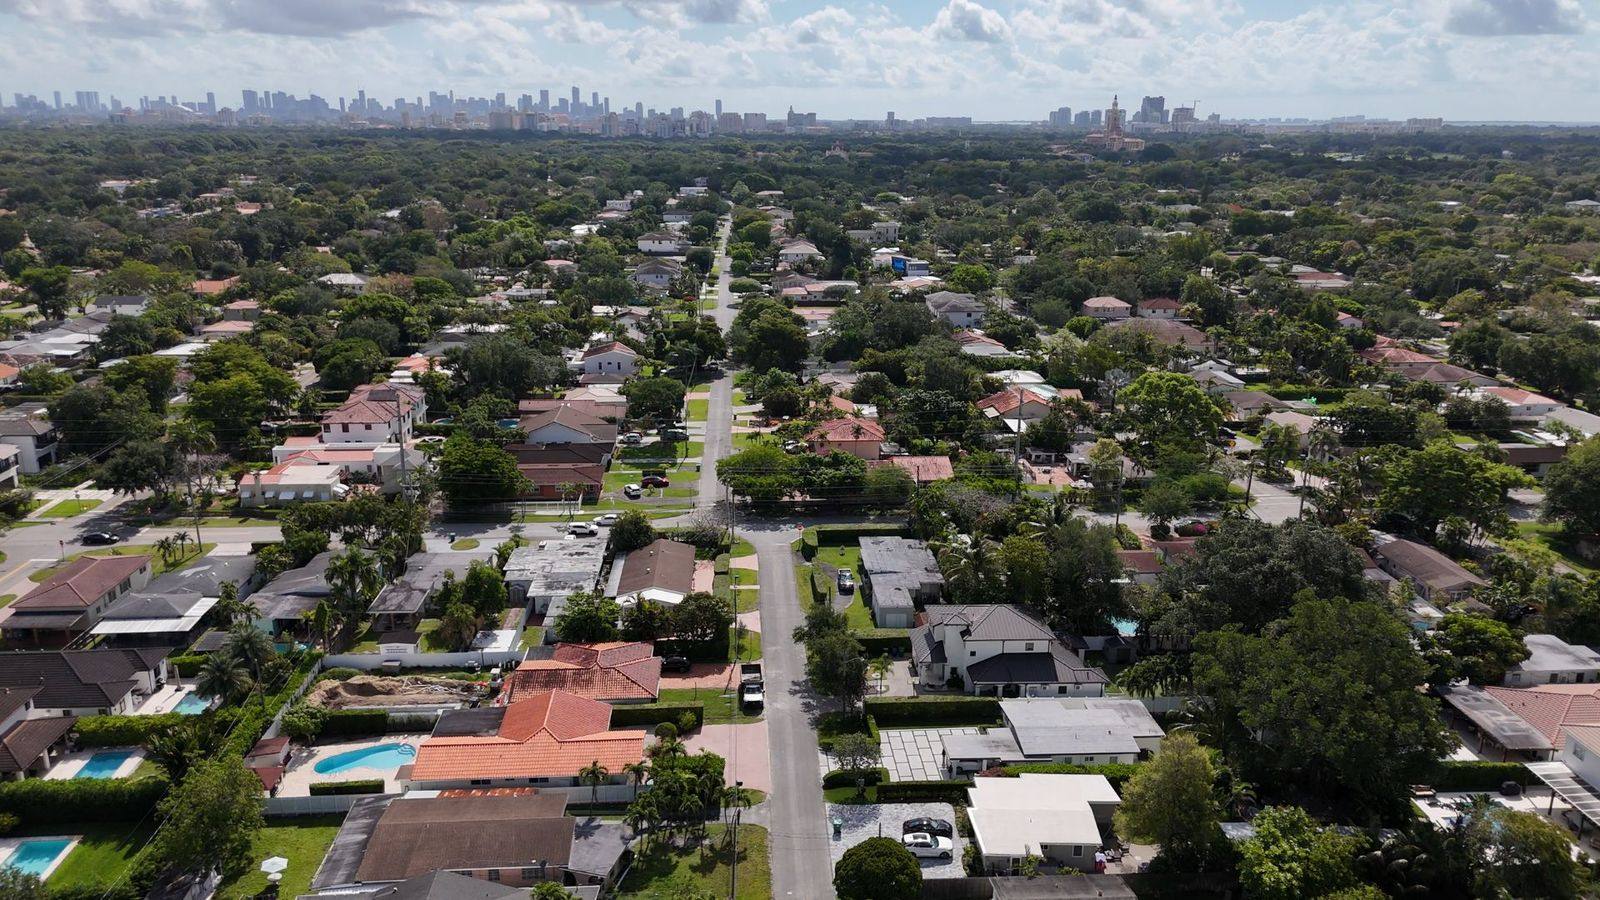
FEMA assigns every parcel a flood zone. Homes in the high-risk A and V zones need flood insurance if the mortgage is federally backed. Homes in Zone X, which FEMA describes as moderate to minimal hazard, usually do not. That is the situation for most of Schenley Park and Coral Terrace, an inland, unincorporated part of Miami-Dade County between Coral Gables and Westchester.
Minimal is not zero. FEMA reports that 29 percent of National Flood Insurance Program claims from 2014 to 2024 came from properties outside high-risk zones. In South Florida, water does not have to come from the coast. A heavy summer storm with nowhere to drain can put water inside a house miles from the bay, and that is exactly the kind of loss a homeowners policy excludes.
Zones also change. FEMA revises its maps, and the zone on a specific address can move. Look up your property on the FEMA Flood Map Service Center and in Miami-Dade County’s flood zone tool, and ask your insurance agent whether any pending map update affects you. Check the parcel, not the neighborhood.
Why I still recommend flood insurance in Zone X
I tell every homeowner in this area the same thing: in the lowest-risk zone the coverage is usually inexpensive, and the protection is large. Two local facts work in your favor:
- Zone X pricing. Premiums follow risk, and Zone X is the cheapest place on the map to insure.
- Miami-Dade’s Class 3 rating. Unincorporated Miami-Dade earned a Class 3 rating in FEMA’s Community Rating System, which translates to roughly a 35 percent discount on NFIP flood premiums for policies here.
Get a quote and decide with real numbers. In most cases, the cost of saying yes is small next to the cost of finding out after a storm that the damage is not covered.
What sets your premium now: Risk Rating 2.0
Since FEMA moved to Risk Rating 2.0, NFIP premiums are priced for the individual property, not just its zone. Your number depends on things like the home’s replacement cost, its elevation, its distance to water and the drainage around it. That is why the premium a neighbor pays may have nothing to do with yours.
Three practical points:
- Shop both markets. Florida has an active private flood market. Sometimes private coverage costs less than the federal program, and it can start sooner.
- Watch the waiting period. An NFIP policy generally takes effect 30 days after purchase. Private carriers often work with 10 to 14 days. Do not leave it for the week of closing.
- Know the NFIP’s status. Congress keeps the program running with short-term extensions; the current one runs to December 12, 2026. When the program’s authority lapses, the NFIP cannot sell new policies, so a buyer who needs one should not wait for the last week.
If your wind policy is with Citizens
Citizens Property Insurance now requires its policyholders to carry flood coverage, even outside high-risk zones, on a schedule based on the dwelling’s replacement cost: homes of $400,000 or more since January 1, 2026, and the remaining policies by January 1, 2027. Many Schenley Park homes are above that line. If your windstorm or homeowners policy is with Citizens, ask your agent before your renewal date, not after.
If you are buying in Schenley Park
- Budget it like taxes. Treat the flood quote as part of your monthly cost, next to property tax and homeowners insurance.
- Quote it during due diligence. The 30-day NFIP waiting period does not care about your closing date. See where this fits in the offer-accepted timeline.
- Ask what lowers the premium. Elevation, certified flood vents and the home’s construction can matter. Your insurance agent can tell you which apply.
- Read the seller’s flood disclosure line by line and ask about anything on it.
If you are still deciding on the area, my guide to moving to Schenley Park covers the rest of the picture.
What Florida now requires sellers to disclose
Florida Statute 689.302 took effect on October 1, 2024, and was expanded on October 1, 2025. At or before the time the contract is signed, the seller must give the buyer a written flood disclosure. It states plainly that homeowners policies do not cover flood, and the seller must say:
- whether they have filed a flood insurance claim, including with the NFIP;
- whether they have received federal or other assistance for flood damage; and
- since October 1, 2025, whether they know of flooding that damaged the property while they owned it, even if no claim was ever filed.
Three things sellers get wrong: it is its own document, not a checkbox buried in another form; “I don’t know” is not a safe answer if you do know; and an as-is contract does not remove the duty to disclose known facts.
If you are selling: turn the disclosure into an advantage
For most sellers in this ZIP code, the flood disclosure is good news in writing. Gather your own history before you list: what you filed, what you repaired and when. A clean, specific answer at the start is worth far more than a surprise during the buyer’s inspection or insurance quote. And because the buyer’s insurer will also look at your roof, read my guide to selling with an older roof and the wind mitigation report while you are at it.
Frequently asked questions
Is Schenley Park in a flood zone?
Under current FEMA maps, the Schenley Park and Coral Terrace area of Miami, FL 33155 is in Zone X, the lowest-risk designation. Maps change, so confirm your specific address on the FEMA Flood Map Service Center or Miami-Dade County’s flood zone tool.
Do I need flood insurance in Zone X in Miami-Dade?
Most lenders do not require it in Zone X, but homeowners insurance does not cover flood, and FEMA reports that 29 percent of NFIP claims from 2014 to 2024 came from outside high-risk zones. Citizens policyholders face their own flood requirement. In Zone X a policy is usually inexpensive, so it is worth a quote.
How long does it take for flood insurance to start?
An NFIP policy generally has a 30-day waiting period. Private flood policies often start in 10 to 14 days. Buyers should get a quote during the inspection period, not the week of closing.
What do Florida sellers have to disclose about flooding?
Under Florida Statute 689.302, at or before the contract the seller gives the buyer a written flood disclosure stating whether they filed a flood insurance claim, whether they received assistance for flood damage and, since October 1, 2025, whether they know of flooding that damaged the property during their ownership.
Does Citizens Property Insurance require flood insurance?
Yes, on a phased schedule. Citizens policyholders with dwellings valued at $400,000 or more must carry flood coverage since January 1, 2026, and the remaining policies by January 1, 2027, even outside high-risk zones.
Whether you are buying or selling in Schenley Park, the paperwork on flooding is more specific than it has ever been. If you want to talk through what it means for your house, I am happy to help.
- Home valuation: Request your home value
- Call or WhatsApp: 305-301-3290
- Bere@BereHomes.com
This article is general information for Miami-Dade homeowners, not legal or insurance advice. Flood maps, premiums and insurer rules change; confirm your situation with a licensed insurance agent, and for how the disclosure law applies to you, talk to a Florida real estate attorney.
Prefer I reach out?
Leave your details and I’ll get back to you the same business day.
Rather pick a time? Book a 15-minute call
Berenice Elguezabal
REALTOR® · Coldwell Banker Realty · Since 2001 · FL Lic. SL0695500
★ Int’l President’s Circle 2025 · Top 4% Nationwide
$150M+ career sales · 250+ closed · 7 sold in Schenley Park